Putting All Your Freight in One Basket: The Competitive Risk of Over-Relying on a Single Carrier
There is a seductive logic to carrier consolidation. Ship everything with one provider, or perhaps two, and you earn volume discounts, simplify your accounts payable process, and reduce the operational overhead of managing multiple relationships. For a business that is growing quickly and lacks dedicated logistics staff, the appeal is genuine.
But this logic has a shelf life. At a certain point — and for many US businesses, that point arrives earlier than expected — carrier concentration stops being a simplification strategy and starts being a liability. The question worth asking is not whether consolidation offers short-term convenience. It clearly does. The question is what that convenience costs over time, and whether the businesses paying that cost fully understand what they are giving up.
The Illusion of Leverage in a Consolidated Relationship
When a business ships 90 percent or more of its parcel volume through a single major carrier, the conventional expectation is that this concentration creates negotiating leverage. In practice, the dynamic often operates in reverse.
Major national carriers — the household names that dominate US parcel and ground shipping — have sophisticated account management systems that are very good at identifying customers with limited alternatives. A shipper who has built their technology stack, customer-facing delivery promises, and operational workflows around a single carrier is not a strong negotiating partner at rate review time. They are a captive account. The carrier knows it. The shipper, often, does not fully reckon with it.
The result is a rate environment that deteriorates gradually. Annual general rate increases — which the major carriers implement each January with remarkable consistency — apply to the base rates from which discounts are calculated. If those base rates rise faster than the discount percentage improves, the effective rate paid per shipment increases regardless of what the contract appears to say. Businesses without alternative carrier relationships have no practical mechanism to push back.
Service Disruptions Are Not Hypothetical
Beyond pricing, the operational risk of carrier concentration deserves more serious attention than it typically receives in logistics planning discussions. Service disruptions at major carriers — whether driven by labor action, extreme weather, technology failures, or capacity constraints during peak demand — are not rare events. They are recurring features of the US logistics landscape.
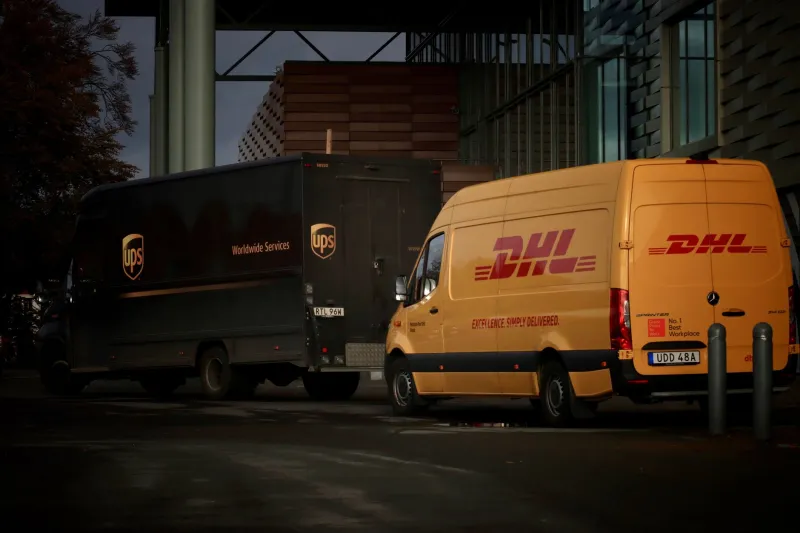
In 2023, the extended uncertainty around a potential UPS labor stoppage prompted a wave of businesses to accelerate carrier diversification plans that had previously been treated as low-priority. Those that had already established alternative carrier relationships were able to reroute volume with minimal disruption. Those that had not faced a difficult choice between absorbing the uncertainty or executing an emergency transition under pressure — which is among the most expensive ways to change logistics providers.
The lesson is not that any particular carrier is unreliable. It is that no carrier, regardless of scale or reputation, is immune to disruption. A supply chain that has no contingency for the failure of its primary shipping partner is a supply chain that has accepted a risk it may not have explicitly chosen to accept.
What Regional and Specialized Carriers Actually Offer
One of the more persistent misconceptions in US shipping strategy is that regional and specialized carriers are inherently inferior alternatives — options to consider only when the major carriers cannot accommodate volume. This framing significantly understates what these providers bring to a diversified carrier strategy.
Within their operating geographies, regional carriers frequently offer transit times that match or exceed national carrier performance, at rates that are meaningfully more competitive. A regional carrier operating in the Southeast, for example, may deliver to addresses in Florida, Georgia, and the Carolinas in one or two days from a regional distribution point — identical to what a national carrier would promise, but at a lower effective rate and with more accessible customer service when exceptions occur.
Specialized carriers — those focused on specific freight types, temperature-controlled shipments, oversized items, or high-value goods — offer a different kind of value. For businesses shipping products that fall outside the standard parcel envelope, a specialized provider often delivers better handling, lower damage rates, and liability structures that are more appropriate to the product being shipped. The cost per shipment may be higher than a general parcel rate, but the total cost including damage claims and customer replacements frequently favors the specialist.
Building a Carrier Mix That Reflects Business Reality
Strategic carrier diversification does not mean fragmenting volume indiscriminately across a dozen providers. It means constructing a carrier portfolio that aligns with the geographic distribution of your customer base, the physical characteristics of your products, your service level commitments, and your risk tolerance.
A practical diversification framework for most US businesses involves three tiers. A primary national carrier handles the bulk of standard parcel volume and provides the broadest geographic reach. One or two regional carriers cover the zones or geographies where they offer demonstrably better rates or service levels. A specialized or contingency carrier — pre-qualified and integrated into your shipping platform — provides overflow capacity and alternative routing when primary options are constrained.
This structure requires more upfront investment in carrier qualification and system integration than a single-carrier approach. It also requires ongoing management attention to ensure that volume allocation remains deliberate rather than drifting back toward concentration by default. The operational overhead is real. So is the return.
The Competitive Dimension That Is Frequently Overlooked
The conversation about carrier diversification is typically framed around risk management — avoiding the downside of disruption or rate deterioration. That framing is accurate but incomplete. Carrier diversification is also a source of competitive advantage, and that dimension deserves equal emphasis.
Businesses with diversified carrier relationships can offer customers delivery options — speed tiers, delivery windows, carrier preferences — that single-carrier shippers cannot match. They can respond to regional demand surges with targeted capacity rather than system-wide constraints. They can test new service offerings in specific markets without committing their entire shipping operation to an untested provider. And they are better positioned to adopt emerging delivery models — including same-day, evening delivery, and returns consolidation services — that are increasingly offered by regional and specialized providers ahead of the national carriers.
In an e-commerce environment where delivery experience is a direct driver of customer retention and repeat purchase rate, the ability to offer differentiated shipping options is not a peripheral benefit. It is a revenue-relevant capability.
The Moment to Diversify Is Before You Need To
The businesses that manage carrier concentration most effectively share a common characteristic: they expanded their carrier relationships before a crisis forced the issue. Carrier qualification, contract negotiation, and technology integration all take time. Attempting to execute these steps under the pressure of a service disruption or a rate dispute produces worse outcomes than deliberate, proactive expansion.
For businesses currently operating with high carrier concentration, the practical starting point is an honest assessment of where that concentration creates exposure. Which carrier handles the volume your business could not function without? What is your contingency if that carrier experiences a service disruption of 72 hours or more? What would a 10 percent rate increase from that provider cost on an annualized basis, and do you have a credible alternative?
The answers to those questions will tell you more about your actual logistics risk profile than any rate card review. And they are the right foundation for building a carrier strategy that is genuinely competitive rather than merely convenient.